The future of real estate over the next decade looks less like a single trend and more like five separate forces converging on the same industry at once, each one already visible today, none of them slowing down.
What's Inside
- The short answer
- The demographic shift: housing between the family home and aged care
- The untethered workforce
- Climate risk, repriced down to the parcel
- The supply-side constraint that isn't going away
- Technology as infrastructure, not a feature
- What this means for how you plan
- Frequently asked questions

The future of real estate is best understood as five structural forces playing out over years, not a single headline trend to watch for. Unlike the shorter-term market snapshots elsewhere on this site, these shifts move slowly and don't reverse easily once underway, which makes them worth understanding even if they won't change next quarter's numbers.
Quick honesty note
This is a long-term thought-leadership piece, not near-term market analysis. For current 2026 data, see real estate market trends & predictions for 2026. Specific projections below reflect forecasts current as of research, which get revised as new data emerges.
The Short Answer
The Demographic Shift: Housing Between the Family Home and Aged Care
Aging populations across developed economies are driving demand for a category of housing that doesn't fit neatly into either a traditional family home or a residential aged-care facility, co-living arrangements, accessible design built in from the start, and proximity to services rather than proximity to an employer, since retirees no longer need a commute to factor into where they live. This is a genuinely structural shift in what kind of housing product gets built and where, not a temporary preference.
The Untethered Workforce

If where you live is no longer determined by where your employer is located, regional and lifestyle markets become genuinely competitive against expensive capital cities in a way they simply weren't before. One detailed model projects office space demand could fall by up to 20% by 2030 compared to 2019, and retail space demand by as much as 22% over the same period, while residential demand holds up considerably better, continuing to grow in most major cities, just more slowly than it would have without this shift. Urbanization itself is evolving alongside this: global megacities still attract capital and talent, but smaller cities and suburban nodes are increasingly becoming genuine innovation hubs in their own right, a more polycentric pattern replacing the dominant single downtown core of previous decades.
Climate Risk, Repriced Down to the Parcel

Climate change has moved from a distant policy concern to a present-day operational and financial one, directly affecting asset values, insurance premiums, tenant demand, and where capital is willing to flow at all. What's genuinely new is the granularity: climate risk mapping is increasingly informing underwriting, zoning, and insurance pricing at the individual parcel level, not just by broad region, meaning two similar properties on the same street can face meaningfully different insurance costs based on specific exposure.
Coastal and wildfire-prone properties in particular are already being repriced by insurance markets in ways that affect both current owners and future buyers. The scale here is worth appreciating: real estate represents an estimated $111 trillion in value across OECD countries alone, nearly double total GDP, which is exactly why climate exposure has become a central, unavoidable underwriting question rather than a niche concern.
The Supply-Side Constraint That Isn't Going Away
Even where demographic demand for new housing is well understood, actually building enough of it has proven consistently difficult. Germany offers a concrete, illustrative example: a target of 320,000 new homes per year through 2030 was set based on clear demographic and regional demand data, yet current approval rates suggest that target is unlikely to be met, due to high construction and material costs, labor shortages, and slow, overlapping approval processes. This pattern, demand clearly outpacing the industry's practical capacity to build, shows up in various forms across many developed markets, and is a genuinely structural constraint rather than a temporary bottleneck likely to resolve on its own.
Technology as Infrastructure, Not a Feature
This shift extends beyond any single tool or platform, it describes technology becoming embedded infrastructure across how the entire industry functions, with investors and regulators increasingly expecting the transparency that data-driven systems make possible. Alongside this, new ownership and access models are emerging: build-to-rent communities delivering purpose-built rental housing at scale rather than converted single-family homes, fractional ownership structures lowering the capital required to participate, discussed further in how to invest in real estate without buying property, and construction methods like 3D printing compressing timelines that have historically been a major constraint on new supply.
What This Means for How You Plan
- Don't treat climate exposure as someone else's problem. Parcel-level risk assessment means insurance costs can already vary significantly between similar nearby properties.
- Watch smaller, lifestyle-oriented markets, not just major metros. The untethered workforce genuinely redistributes demand rather than simply shrinking it.
- Expect housing product types to diversify. Demand for co-living and accessible, service-proximate housing will keep growing alongside traditional single-family stock.
- Don't assume new supply will simply appear where demand exists. Labor, cost, and approval constraints are structural, not temporary.
- Treat technology fluency as a baseline skill, not a specialization. It's becoming foundational to how the industry operates, not an optional add-on.
Frequently Asked Questions
How will an aging population change what kind of housing gets built?
It's driving demand for housing between a traditional family home and residential aged care, co-living arrangements, accessible design, and proximity to services rather than to employment, since retirees no longer need to factor in a commute.
Will remote work permanently change where people choose to live?
It appears to be having a lasting effect. When location isn't dictated by an employer, regional and lifestyle markets become genuinely competitive against expensive capital cities, contributing to a more polycentric pattern of urban development.
How is climate change affecting real estate values and insurance?
Climate risk mapping is increasingly informing underwriting and insurance pricing at the individual parcel level, meaning similar nearby properties can face meaningfully different costs based on specific exposure to flooding, wildfire, or other hazards.
Why isn't new housing supply keeping up with demand in many markets?
High construction and material costs, labor shortages, and slow or complex approval processes are structural constraints that limit how quickly new supply can be built, even where demographic demand is clearly documented.
Is proptech just a passing trend in real estate?
Most industry analysis suggests otherwise. Technology is increasingly described as foundational infrastructure reshaping how real estate is developed, operated, marketed, and traded, rather than a niche or optional feature.
What new ways to access real estate are emerging?
Build-to-rent communities built at scale specifically for renters, fractional ownership models that lower the capital required to participate, and construction methods like 3D printing that compress timelines are all emerging alongside traditional ownership.
Structural Change Moves Slowly, But It Doesn't Stop
The future of real estate isn't a single prediction to get right, it's five forces already reshaping the industry that are worth tracking regardless of what next quarter's data shows. Demographic shifts, a workforce no longer tied to one city, climate risk repriced down to the parcel, persistent supply constraints, and technology becoming foundational infrastructure will all keep shaping decisions long after any single year's headlines fade.
Take This Further
Books by Nwaeze David to help you build real wealth through property.
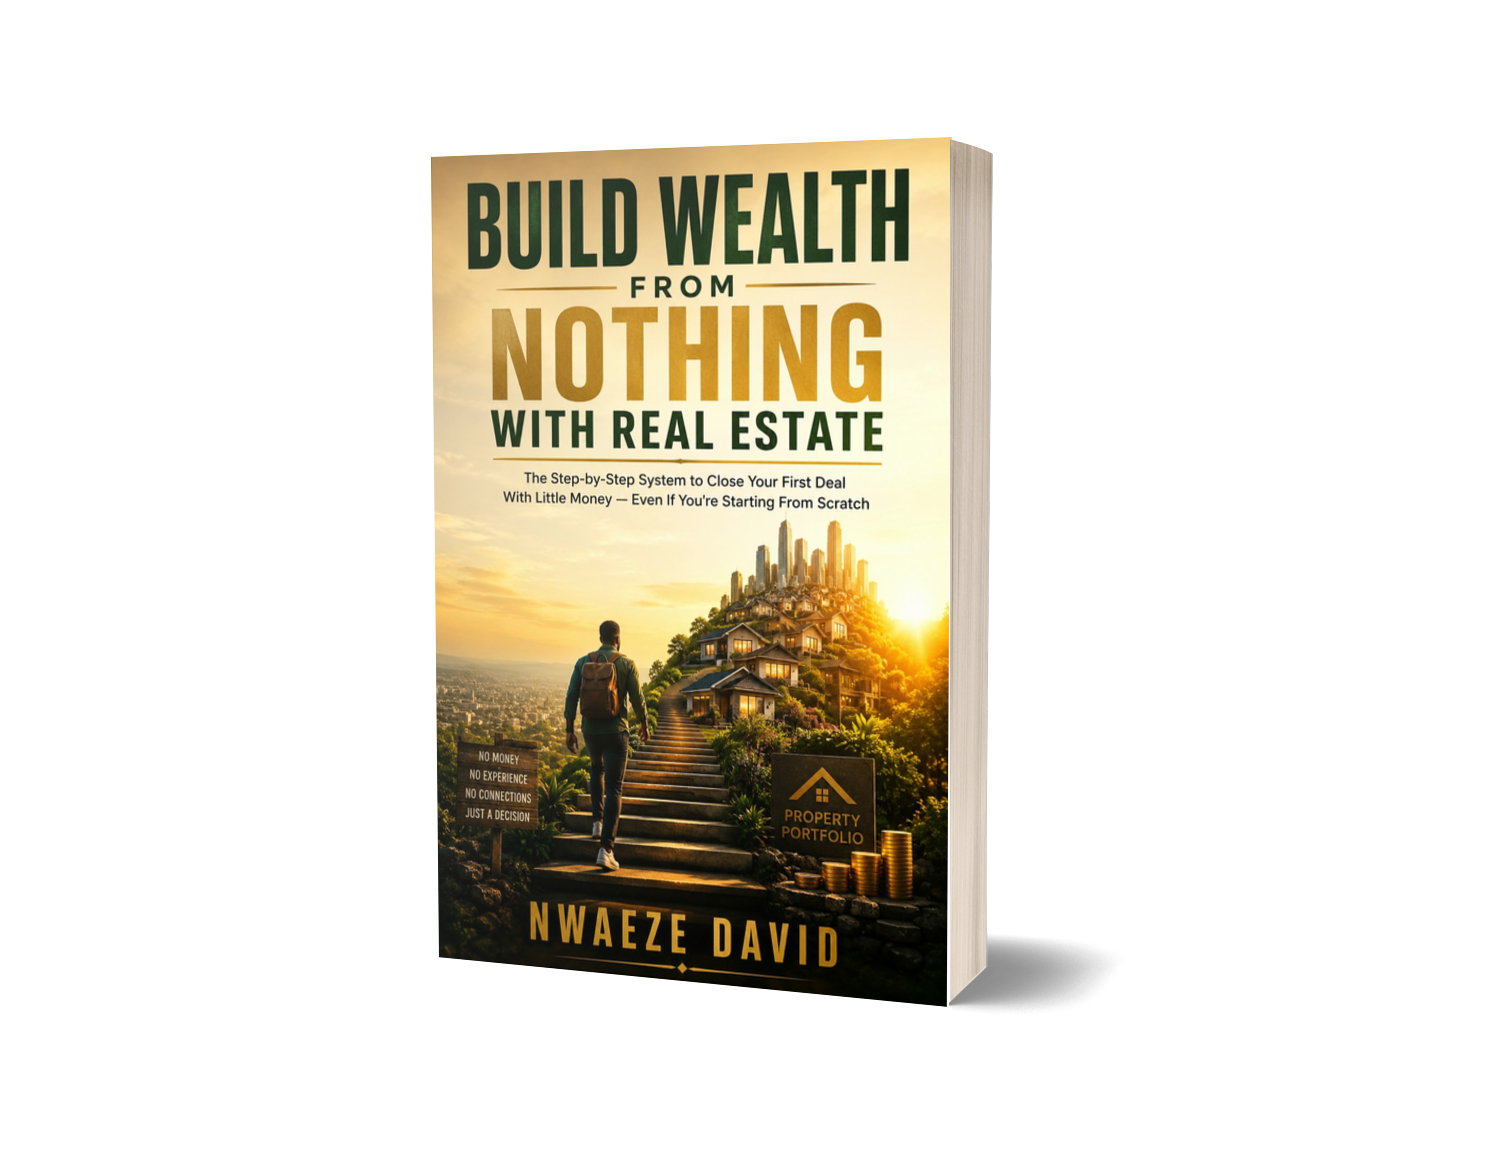
"You don't need a big deposit, perfect credit, or family money to build wealth in real estate. You need a system, the resourcefulness to work it, and the courage to start."
Get Your Copy →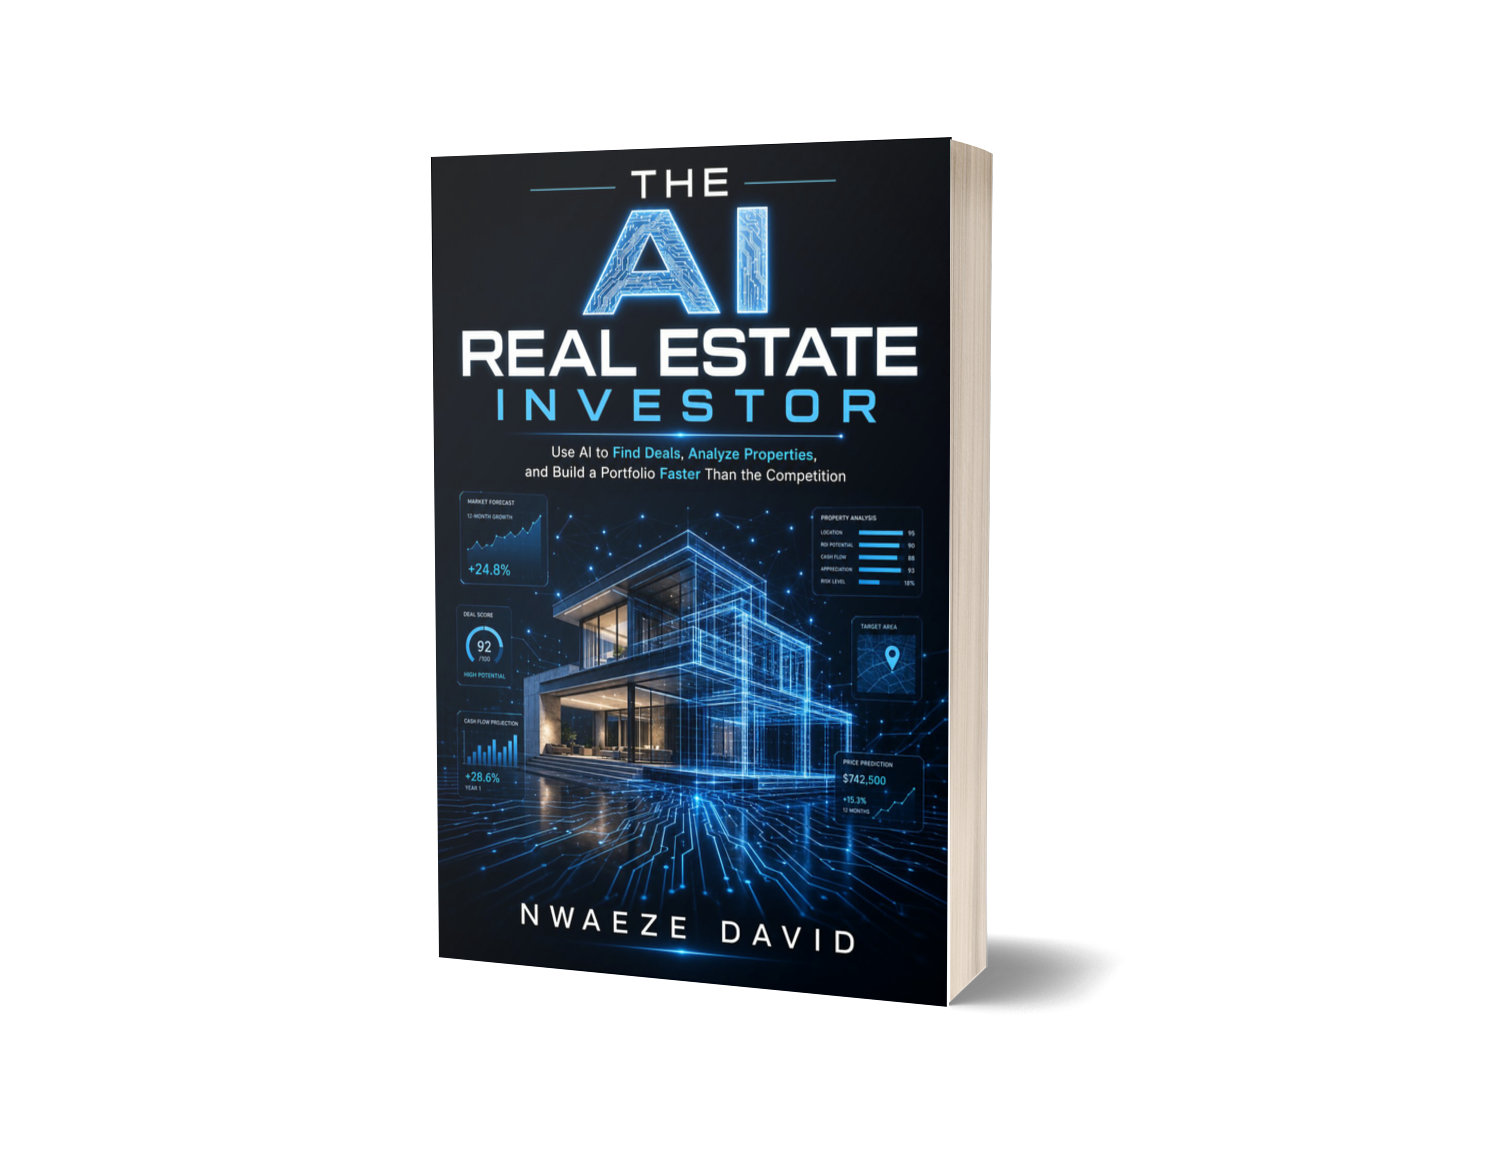
"The AI Real Estate Investor gives you that system. It shows you exactly how to point AI at the parts of your business that actually make money."
Get Your Copy →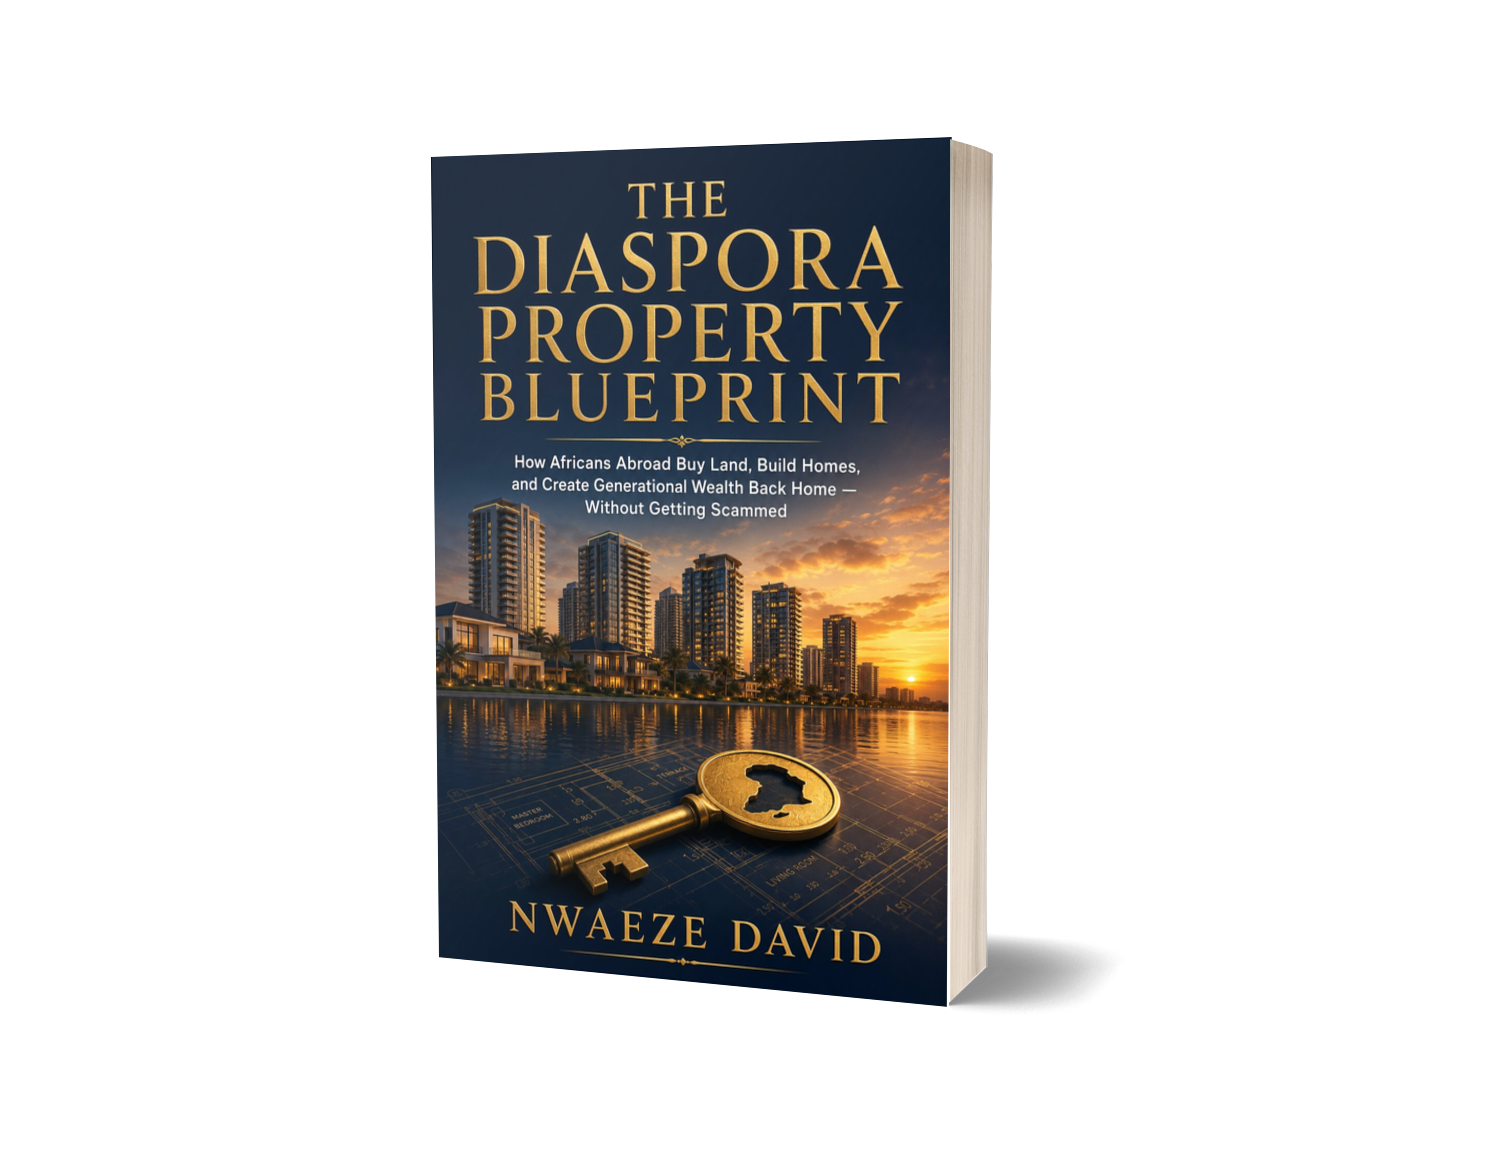
"The Diaspora Property Blueprint is the complete, step-by-step system for buying land and building wealth back home safely, from anywhere in the world."
Get Your Copy →Get help thinking about where these trends point for you
Join the newsletter for practical, no-hype breakdowns of what's actually happening in real estate, then step inside the private community where we talk through how these longer-term shifts might shape your own strategy.
Keep learning: real estate market trends & predictions for 2026 · how to invest in real estate without buying property · AI tools every real estate investor should know.
Education only, a long-term thought-leadership perspective rather than near-term market analysis. Structural forecasts, demand projections, and valuation figures cited here reflect research current as of writing and get revised as new data emerges; figures are marked for verification where noted.
Written by
Nwaeze David
Nigerian digital entrepreneur, educator and author of three real estate books. He writes practical, honest guides for new investors, working realtors and Africans building back home from abroad.


