A DSCR loan qualifies you on what the property earns, not what your paycheck says. No tax returns, no W-2s, no personal income verification, just the rent versus the payment. Here is exactly how it works, what it costs, and the one clause almost every borrower skips reading.
What's Inside
- What a DSCR loan is
- How DSCR is calculated
- DSCR loan requirements
- DSCR vs conventional loans
- The prepayment penalty almost nobody reads closely
- DSCR loans for foreign nationals and diaspora investors
- Who should (and shouldn't) use a DSCR loan
- How to get approved
- Common mistakes
- Frequently asked questions

A DSCR loan (debt service coverage ratio loan) qualifies you based on a rental property's income, not your personal income, employment history, or tax returns.
If the rent comfortably covers the mortgage payment, you can often close in three to four weeks with none of the paperwork a conventional loan demands.
This guide covers exactly how the ratio is calculated, what lenders actually require, how DSCR compares to a conventional investment loan, and a feature almost every DSCR product includes that surprises borrowers who did not ask about it upfront.
Quick honesty note
This is education, not financial advice. DSCR loans are non-QM products, meaning requirements, rates, and terms vary considerably between lenders with no standardized rulebook. Every figure below is a common range, not a universal rule. Confirm current terms directly with a lender before applying.
What a DSCR Loan Is
In short: A DSCR loan is a mortgage for rental property that qualifies you based on the property's rental income relative to its debt payment, rather than your personal income, tax returns, or employment.
It falls under the non-QM (non-qualified mortgage) category, built specifically for real estate investors whose personal financial picture does not fit conventional lending boxes.
How DSCR Is Calculated

The formula
DSCR = Monthly gross rental income ÷ Monthly PITIA (principal, interest, taxes, insurance, and association dues if any).
A DSCR of 1.0 means rent exactly covers the payment. A DSCR of 1.25 means rent covers the payment with a 25% surplus.
Example: a property renting for $2,500 a month against a $2,000 PITIA payment has a DSCR of 1.25, generally considered the sweet spot for the best available rates and leverage.
DSCR Loan Requirements
Swipe to see more →
| Factor | Typical range |
|---|---|
| Minimum DSCR | 0.75-1.0 (aggressive programs); 1.25+ for best pricing |
| Down payment / LTV | 20% down (80% LTV) most common; some as low as 15%, others cap at 70-75% LTV |
| Credit score | 620-680 minimum; sub-640 often declined outright |
| Cash reserves | 3-6 months of PITIA, sometimes more for multiple properties |
| Interest rate | Roughly 1-2 percentage points above a conventional investment loan; commonly 7-9% currently |
| Closing timeline | 21-30 days, versus 45+ days for a conventional investment loan |
| Property count limit | None, unlike conventional financing's 10-property cap |
Many programs also accept projected short-term rental income, verified through platforms like AirDNA or comparable market data, which makes DSCR financing a common choice for Airbnb-style purchases too. See how to start an Airbnb business.
DSCR vs Conventional Loans
Swipe to see more →
| Factor | DSCR loan | Conventional loan |
|---|---|---|
| Qualifies on | Property's rental income | Your personal income and DTI |
| Tax returns / W-2s | Not required | Required |
| Number of properties | No cap | Capped at 10 (Fannie Mae/Freddie Mac) |
| Closing speed | 21-30 days | 45+ days typical |
| Rate | 1-2 points higher | Lower, but stricter DTI qualifying |
| Prepayment penalty | Common (3-5 years) | Rare |
Full detail on the conventional side in how to get a mortgage for an investment property, and on scaling past the conventional cap in how to build a real estate portfolio from scratch.
The Prepayment Penalty Almost Nobody Reads Closely

Most DSCR loans include a prepayment penalty, a fee charged if you sell, refinance, or make large principal paydowns before an agreed period ends, commonly three to five years.
This exists because DSCR loans are non-QM products often held in portfolio or sold to investors expecting a certain interest income stream; paying off early disrupts that math for the lender.
- Step-down structures. The most common: a 3-year schedule (3%-2%-1%) or 5-year schedule (5%-4%-3%-2%-1%), with the penalty shrinking each year and disappearing after the term ends.
- Flat percentage. Commonly 5% of the outstanding balance, regardless of which year within the term you exit.
- Six-month interest penalty. A fee equal to six months of interest, often cheaper than a flat 5% penalty in the earliest years.
Match the term to your actual plan
Longer prepayment terms buy you a lower rate; shorter terms or no-penalty options cost more upfront but protect your flexibility.
If you plan a long-term hold, a 5-year penalty term is usually the cheapest choice, since you were unlikely to sell early anyway.
If you plan to refinance or sell within a few years, a shorter term or a no-penalty option, even at a rate premium, often saves money overall.
Most programs allow partial paydowns up to 20% of the original balance per year without triggering the fee, and regular monthly payments never trigger it.
DSCR Loans for Foreign Nationals and Diaspora Investors
This is one of the most useful, and least publicized, applications of DSCR lending. Because the underwriting focuses on the property's income rather than your personal financial history, DSCR loans have become a genuinely accessible path for foreign nationals and diaspora investors to finance US rental property, including for Africans abroad wanting to build income-producing real estate in the US without US credit history or a Social Security Number.
- No SSN required in most cases. An ITIN (Individual Taxpayer Identification Number) works for many programs; some lenders require neither.
- No US residency, visa, or green card needed. Owning US property does not require or grant any immigration status.
- Larger down payment typically required. Commonly 25-30% (70-75% LTV) for foreign national programs, versus 20-25% for domestic borrowers.
- Usually purchased through a US-based LLC. Most foreign national programs require the loan to close in an entity's name rather than personally.
- Documentation replaces US tax history. Expect to provide a passport, several months of foreign bank statements, and proof of funds instead of US tax returns.
- Remote closing is standard. Most foreign national DSCR closings happen via mail-away notarization or e-signature, with no US travel required.
If you are researching this specifically as an African or diaspora investor, pair this with the fuller picture in diaspora real estate investment and how to form an LLC for real estate investing, since holding the property in an LLC is typically required for this route.
Who Should (and Shouldn't) Use a DSCR Loan
DSCR fits well for: self-employed investors whose tax returns understate their real cash flow, investors scaling past the conventional 10-property cap, foreign nationals and ITIN holders without US credit history, and anyone buying through an LLC for liability protection.
DSCR is usually the wrong tool for: a property that does not yet cash flow, such as new construction or a heavy rehab (hard money fits better here), or a purchase needing an extremely fast close of a week or two (hard money is typically faster still). See hard money loans for that comparison.
How to Get Approved
- Run the DSCR math before you shop. Divide the property's realistic monthly rent by the estimated full PITIA payment. Anything below 1.0 will need a specialized no-ratio program or a larger down payment.
- Check your credit. Even without income verification, most lenders still want a minimum score, commonly 620-680.
- Decide your prepayment structure upfront. Match the term to your realistic hold period, not just the lowest advertised rate.
- Gather property-level documents. A lease if tenanted, or a market rent schedule from an appraiser if vacant.
- Set up your LLC if required. Many programs, and most foreign national programs specifically, require closing in an entity's name.
- Compare more than one lender. DSCR pricing varies more between lenders than conventional financing does, since there is no standardized rulebook.
Common Mistakes (and How to Dodge Them)
- Ignoring the prepayment penalty entirely. Focusing only on the rate can cost you a five-figure fee if you exit the loan early.
- Using optimistic rent estimates. Underwrite with a realistic, comparable-supported rent, not a hopeful number.
- Assuming DSCR is always cheaper than conventional. It is usually more expensive in rate, its advantage is speed and flexible qualifying, not price.
- Not confirming state availability. Some DSCR lenders do not operate in every state, and a few states have broker licensing restrictions that limit options further.
- Skipping the LLC step for foreign national programs. Most require entity ownership; set this up before you are mid-underwriting.
Frequently Asked Questions about DSCR Loans
What is a good DSCR ratio?
A DSCR of 1.25 or higher is generally considered the sweet spot for the best rates and leverage, meaning the property's rent covers the mortgage payment with a 25% surplus.
A ratio of 1.0 means rent exactly covers the payment and is the standard minimum for most programs, while some aggressive lenders accept ratios as low as 0.75 with a larger down payment or other compensating factors.
Do DSCR loans require income verification?
No. DSCR loans qualify you based on the rental property's income relative to its debt payment, not your personal income, employment history, or tax returns.
This makes them popular with self-employed investors, those with complex tax situations, and foreign nationals without US income documentation.
Are DSCR loan rates higher than conventional loans?
Yes, typically 1 to 2 percentage points higher than a conventional investment property loan, reflecting the reduced documentation and the non-QM classification.
Current rates commonly run in the 7% to 9% range for qualified borrowers, though this varies by lender, DSCR ratio, credit score, and prepayment structure chosen.
What is a DSCR loan prepayment penalty?
A fee charged if you sell, refinance, or make large principal payments before an agreed period ends, commonly three to five years.
Structures include step-down schedules (such as 5%-4%-3%-2%-1%), a flat percentage (often 5%), or a six-month interest charge.
Most programs allow partial prepayments up to 20% of the original balance per year without triggering the penalty.
Can foreign nationals get a DSCR loan for US real estate?
Yes, and DSCR loans are one of the most accessible financing paths for foreign nationals, since underwriting focuses on the property's income rather than US credit history or income documentation.
Foreign national programs typically require a larger down payment (often 25-30%), purchase through a US-based LLC, and documentation like a passport and foreign bank statements instead of US tax returns.
How many DSCR loans can I have at once?
There is no cap on the number of DSCR loans a single investor can hold, unlike conventional financing, which caps an individual investor at 10 financed 1-4 unit properties through Fannie Mae and Freddie Mac. This is one of the main reasons investors scaling a larger portfolio move to DSCR financing.
Let the Property Do the Talking
A DSCR loan shifts the entire qualifying conversation from your paycheck to the property's own numbers, which is exactly why it has become the default tool for investors who do not fit conventional lending boxes, whether that is self-employment, portfolio scale, or simply living outside the US.
Run the ratio honestly, read the prepayment terms as carefully as the rate, and it becomes one of the most flexible financing tools available to a real estate investor.
Take This Further
Books by Nwaeze David to help you build real wealth through property.
"You don't need a big deposit, perfect credit, or family money to build wealth in real estate. You need a system, the resourcefulness to work it, and the courage to start."
Get Your Copy →
"The AI Real Estate Investor gives you that system. It shows you exactly how to point AI at the parts of your business that actually make money."
Get Your Copy →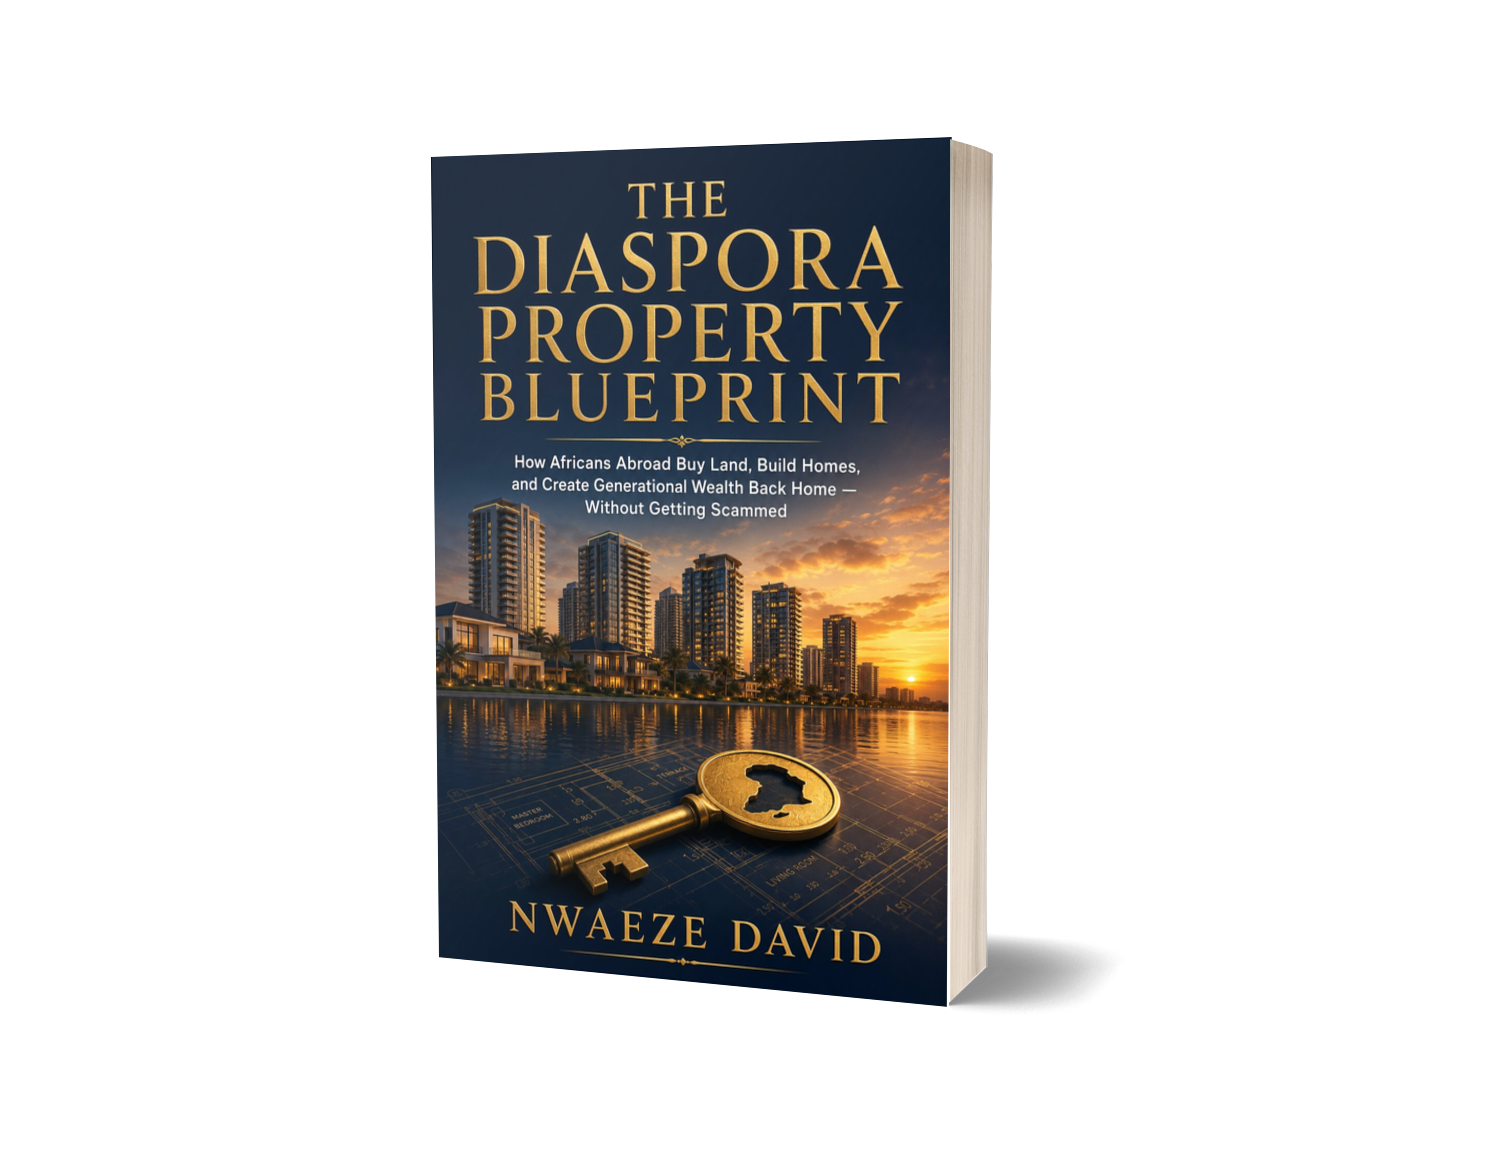
"The Diaspora Property Blueprint is the complete, step-by-step system for buying land and building wealth back home safely, from anywhere in the world."
Get Your Copy →Get help comparing your DSCR options
Join the newsletter for practical, no-hype lessons on financing rentals the smart way, then step inside the private community where we compare real DSCR lenders, real prepayment terms, and the strategy behind scaling with this financing tool.
Keep learning: how to get a mortgage for an investment property · hard money loans · how to form an LLC for real estate investing · diaspora real estate investment · BRRRR method explained.
Education only, not financial advice. DSCR loans are non-QM products with no standardized industry guidelines, requirements, rates, and terms vary considerably by lender, property type, and state; figures here are illustrative and marked for verification where noted. Speak to a licensed lender before applying, and always read the full prepayment penalty terms before signing.
Written by
Nwaeze David
Nigerian digital entrepreneur, educator and author of three real estate books. He writes practical, honest guides for new investors, working realtors and Africans building back home from abroad.