House hacking is the closest thing real estate offers to a genuine cheat code: buy a small multi-unit property, live in one part, and let tenants cover most or all of your mortgage. Here is exactly how the financing works, what it can realistically save you, and where the "live for free" promise gets oversold.
What's Inside

House hacking means buying a small multi-unit property, living in one unit, and renting out the rest so your tenants' rent covers most or all of your housing payment. Because you occupy the property, you qualify for owner-occupied financing with a far lower down payment than any pure investment loan requires, which is exactly what makes this the strongest first move for most beginning investors.
This guide covers the financing mechanics most people get wrong, what house hacking can realistically save you, and the honest version of the "live for free" pitch you see everywhere online.
Quick honesty note
This is education, not financial advice. Loan limits, down payment rules, and mortgage insurance figures shift. "Live for free" is the best-case outcome, not the guaranteed one, treat every dollar figure here as illustrative. Confirm current terms with a lender before making an offer.
What House Hacking Actually Is
How Much Down Payment You Actually Need
This is the entire reason house hacking works: financing rules for owner-occupied properties are dramatically more generous than for pure investment properties.
Swipe to see more →
| Loan type | Down payment | Notes |
|---|---|---|
| FHA | 3.5% | 2-4 units, must occupy one as primary residence |
| Conventional | 5% | 2-4 units, updated in late 2023, no self-sufficiency test |
| VA | 0% | Up to 4 units, eligible veterans and service members only |
Compare that to a pure investment property loan, which typically demands 20-25% down. That gap is the whole strategy in one table.
The FHA Self-Sufficiency Test

If you are using FHA financing on a triplex or fourplex, there is one extra hurdle: the self-sufficiency test. FHA requires that 75% of the total projected rental income from all units (including the one you will live in, at market rent) covers the full monthly housing payment, principal, interest, taxes, insurance, and any HOA dues. The 25% haircut accounts for vacancy and maintenance. If the property fails this test, FHA cannot close the loan, no matter how strong your personal income is.
Duplexes are exempt
The self-sufficiency test applies only to three- and four-unit FHA purchases. A duplex skips it entirely, which is one reason duplexes are often the easiest and fastest entry point into house hacking, especially in higher-rate environments where PITI payments have climbed.
FHA vs Conventional for House Hacking
Swipe to see more →
| Factor | FHA | Conventional |
|---|---|---|
| Down payment | 3.5% | 5% |
| Self-sufficiency test (3-4 units) | Required | Not required |
| Mortgage insurance | Upfront + annual MIP, often life of loan | PMI, cancels near 78-80% LTV |
| Reserve requirement | None for duplex; ~3 months for 3-4 units | Typically 6 months |
FHA tends to win when your down payment is tight or your credit sits in the mid-600s to low-700s. Conventional tends to win once your credit clears roughly 740, when a fourplex fails the FHA self-sufficiency test, or when you would rather avoid mortgage insurance that never cancels. Many house hackers start on FHA, then refinance into a conventional loan once they hit meaningful equity, precisely to drop that lingering MIP. Full financing comparison in conventional vs FHA loan.
How Much Could You Actually Save?

The "live for free" pitch that circulates on social media is real for some house hackers and oversimplified for most. A more honest, common outcome: cutting your effective housing cost by roughly 40% to 70%, not necessarily to zero. Turning a $2,800 mortgage into an effective $1,100 payment by collecting $1,700 in rent from the other units is still a genuinely transformational result, even though it is not literally free.
Underwrite conservatively. Assume 90-95% occupancy across the year (roughly one vacant month), not a perfect 100% rent collection, and you will rarely be disappointed by the real numbers.
Types of House Hacks
- Duplex. The simplest entry point, similar layouts on both sides, no FHA self-sufficiency test, and usually the easiest to finance.
- Triplex or fourplex. More rental income potential per property, but the FHA self-sufficiency test adds a real qualifying hurdle, and conventional financing may be the better fit if the numbers are tight.
- Single-family with rented rooms. Buy a standard home and rent out extra bedrooms. Financing is simpler since it is not a legal multi-unit, but qualifying using boarder income can be harder to document than income from a genuinely separate unit.
- Home with an ADU. An accessory dwelling unit adds a separate rentable space to an otherwise standard home. A 2026 rule change now lets projected ADU rental income count toward your qualifying income on certain conventional loans, opening this option to more buyers.
A Worked Example
A duplex purchased for $380,000 with 3.5% down ($13,300) on an FHA loan. At a current investment-adjacent rate plus MIP, the full monthly payment (principal, interest, taxes, insurance, and mortgage insurance) runs approximately $2,950. The other unit rents for $1,700 a month.
- Full payment: $2,950
- Rental income: $1,700
- Effective housing cost: roughly $1,250 a month
That is a genuine reduction of well over half your housing cost, on a property you also now own, with tenants paying down your mortgage balance every month. In stronger rent markets or with a third or fourth unit, some house hackers do push their effective cost to zero or below. Treat that as the ceiling, not the baseline you plan around.
Common Mistakes (and How to Dodge Them)
- Assuming 100% occupancy. Underwrite with a real vacancy allowance, not a perfect year of rent collection.
- Skipping the self-sufficiency math before making an offer. On a 3-4 unit FHA purchase, run this test before you write the offer, not after, since a failing property cannot close.
- Ignoring landlord responsibilities. You are now managing tenants next door to where you sleep. Screen carefully and set clear expectations from day one.
- Forgetting MIP never cancels on most FHA loans. If you plan to hold long-term, model the cost of that ongoing insurance, or plan your refinance timeline in advance.
- Buying based on the "live for free" headline. Run your own numbers for your specific property and market. Treat a full cost elimination as a bonus outcome, not the plan.
Frequently Asked Questions
What is house hacking?
House hacking means buying a property with two to four units, or a single-family home with rentable space, living in one part as your primary residence, and renting out the rest. Because you occupy the property, you qualify for low-down-payment owner-occupied financing, and the rental income from the other units offsets some or all of your mortgage payment.
How much down payment do I need for house hacking?
FHA loans require as little as 3.5% down on 2-4 unit owner-occupied properties. Conventional loans require about 5% down following a rule change in late 2023 that removed the older, much higher multi-unit down payment requirements. VA loans allow 0% down on up to four units for eligible veterans and service members.
What is the FHA self-sufficiency test?
The FHA self-sufficiency test applies only to three- and four-unit FHA purchases, duplexes are exempt. It requires that 75% of the projected total rental income from all units, including the one you will occupy, cover the full monthly housing payment. If a property fails this test, FHA cannot close the loan regardless of your personal income.
Can house hacking really let you live for free?
Sometimes, but it is not the guaranteed outcome. A more realistic and still valuable result is reducing your effective housing cost by roughly 40% to 70% through rental income from the other units. Some house hackers, especially with three or four units in strong rental markets, do reduce their cost to zero or below, but that should be treated as a possible bonus rather than the plan you underwrite around.
Should I choose FHA or conventional financing for house hacking?
FHA often works better with a tighter down payment or credit in the mid-600s to low-700s range, but it requires mortgage insurance that typically lasts the life of the loan and, on 3-4 units, a self-sufficiency test. Conventional financing usually wins with stronger credit, around 740 or higher, avoids the self-sufficiency test entirely, and its mortgage insurance cancels once you reach roughly 78-80% loan-to-value.
Is a duplex or a fourplex better for a first house hack?
A duplex is usually the easier and faster first step, since it skips the FHA self-sufficiency test and typically has simpler, more comparable unit layouts. A triplex or fourplex offers more total rental income potential, but adds financing complexity and, on FHA loans, a rental-income test the property must pass before the loan can close.
Let Your Tenants Build Your Equity
House hacking will not always make your housing cost disappear, but it consistently does something almost as powerful: it turns your biggest monthly expense into an asset that builds equity while someone else helps pay for it. Run conservative numbers, understand which loan fits your situation, and treat a fully free living situation as a bonus, not the baseline.
Take This Further
Books by Nwaeze David to help you build real wealth through property.
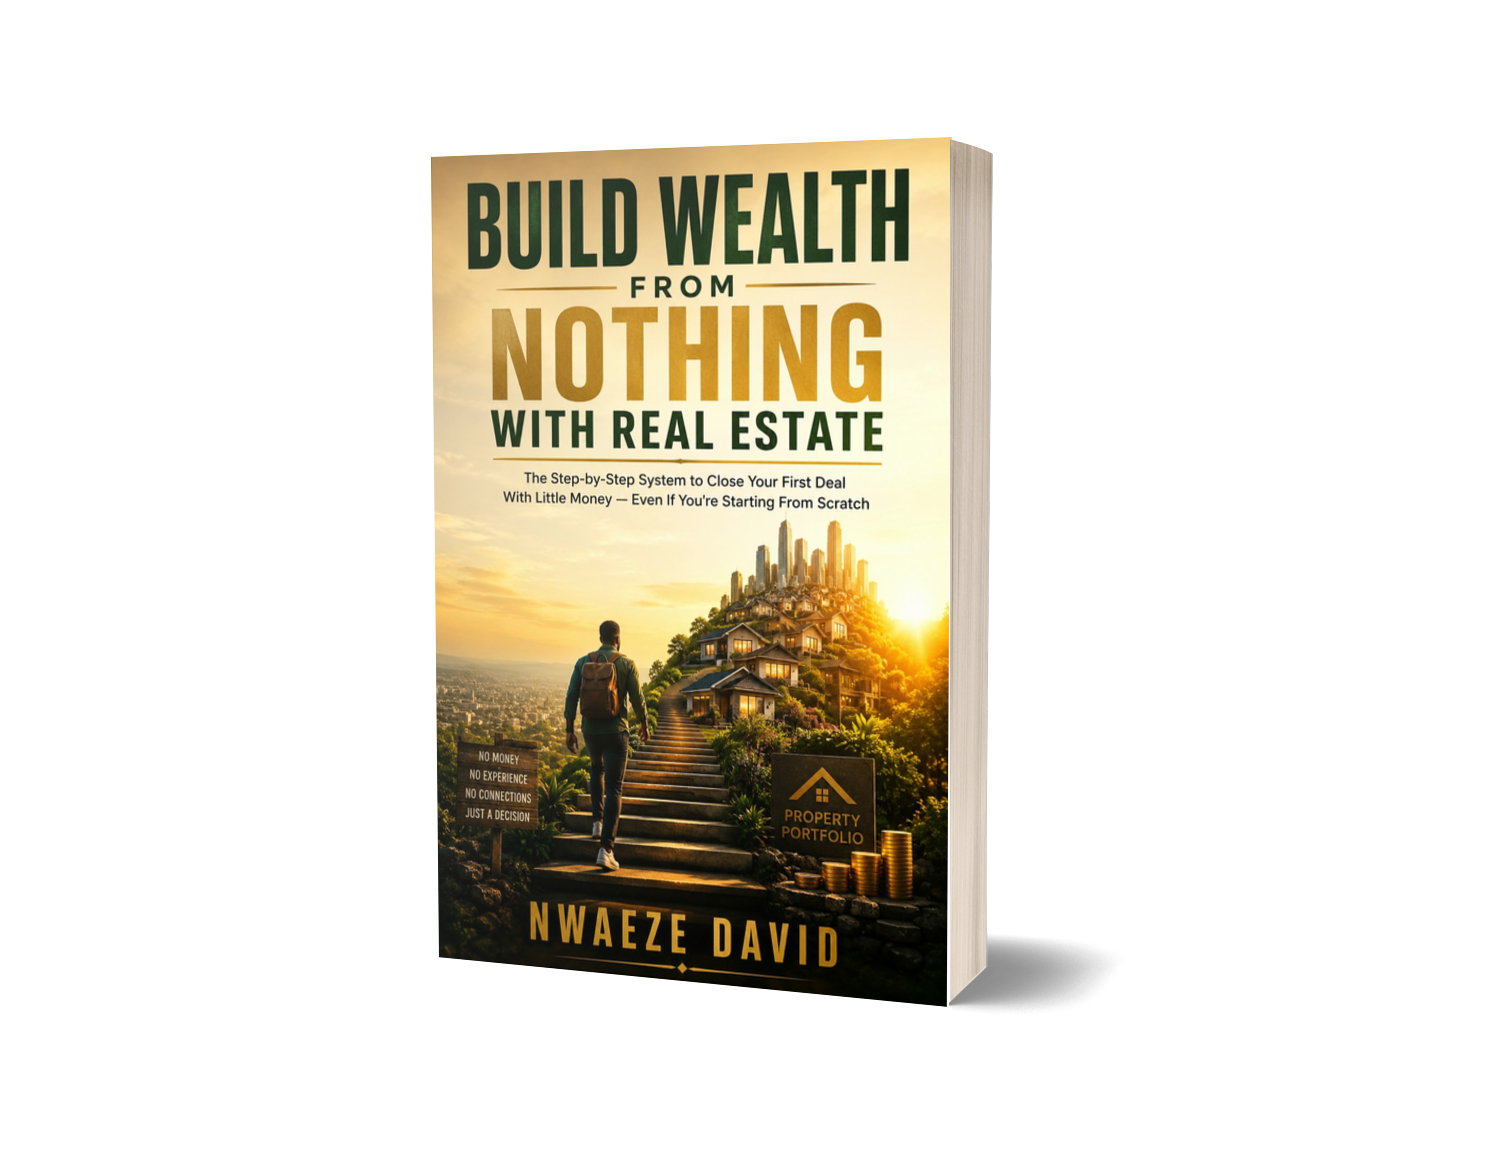
"You don't need a big deposit, perfect credit, or family money to build wealth in real estate. You need a system, the resourcefulness to work it, and the courage to start."
Get Your Copy →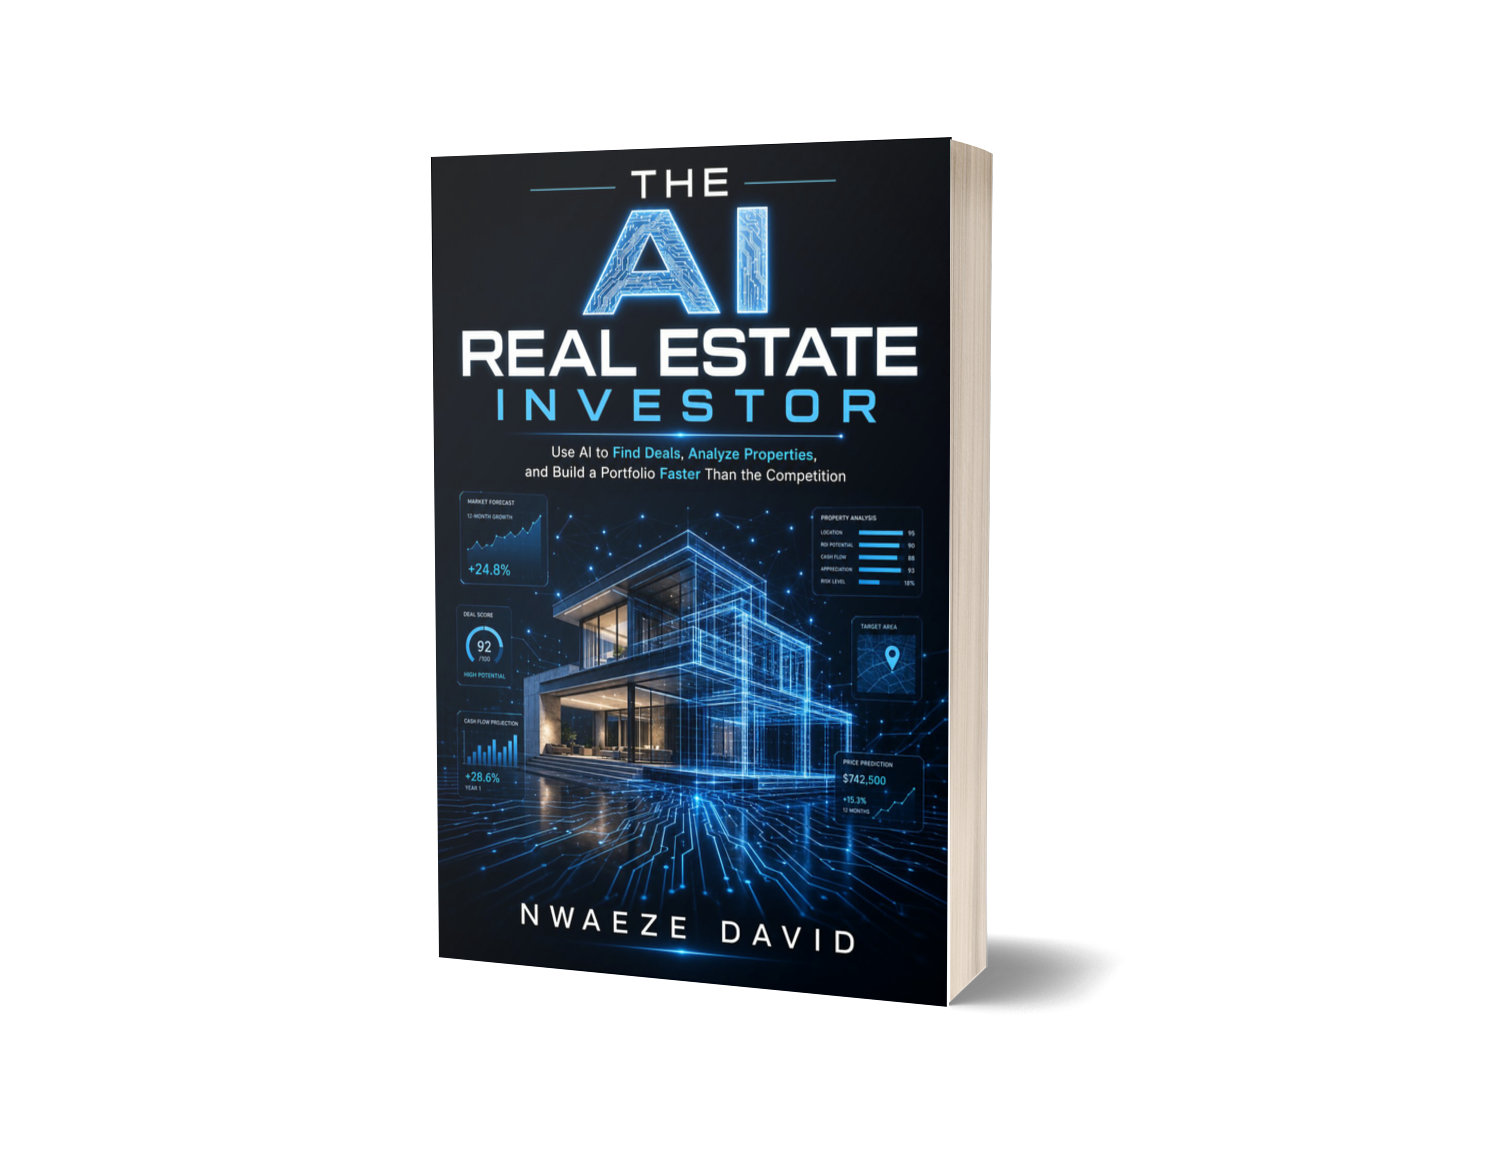
"The AI Real Estate Investor gives you that system. It shows you exactly how to point AI at the parts of your business that actually make money."
Get Your Copy →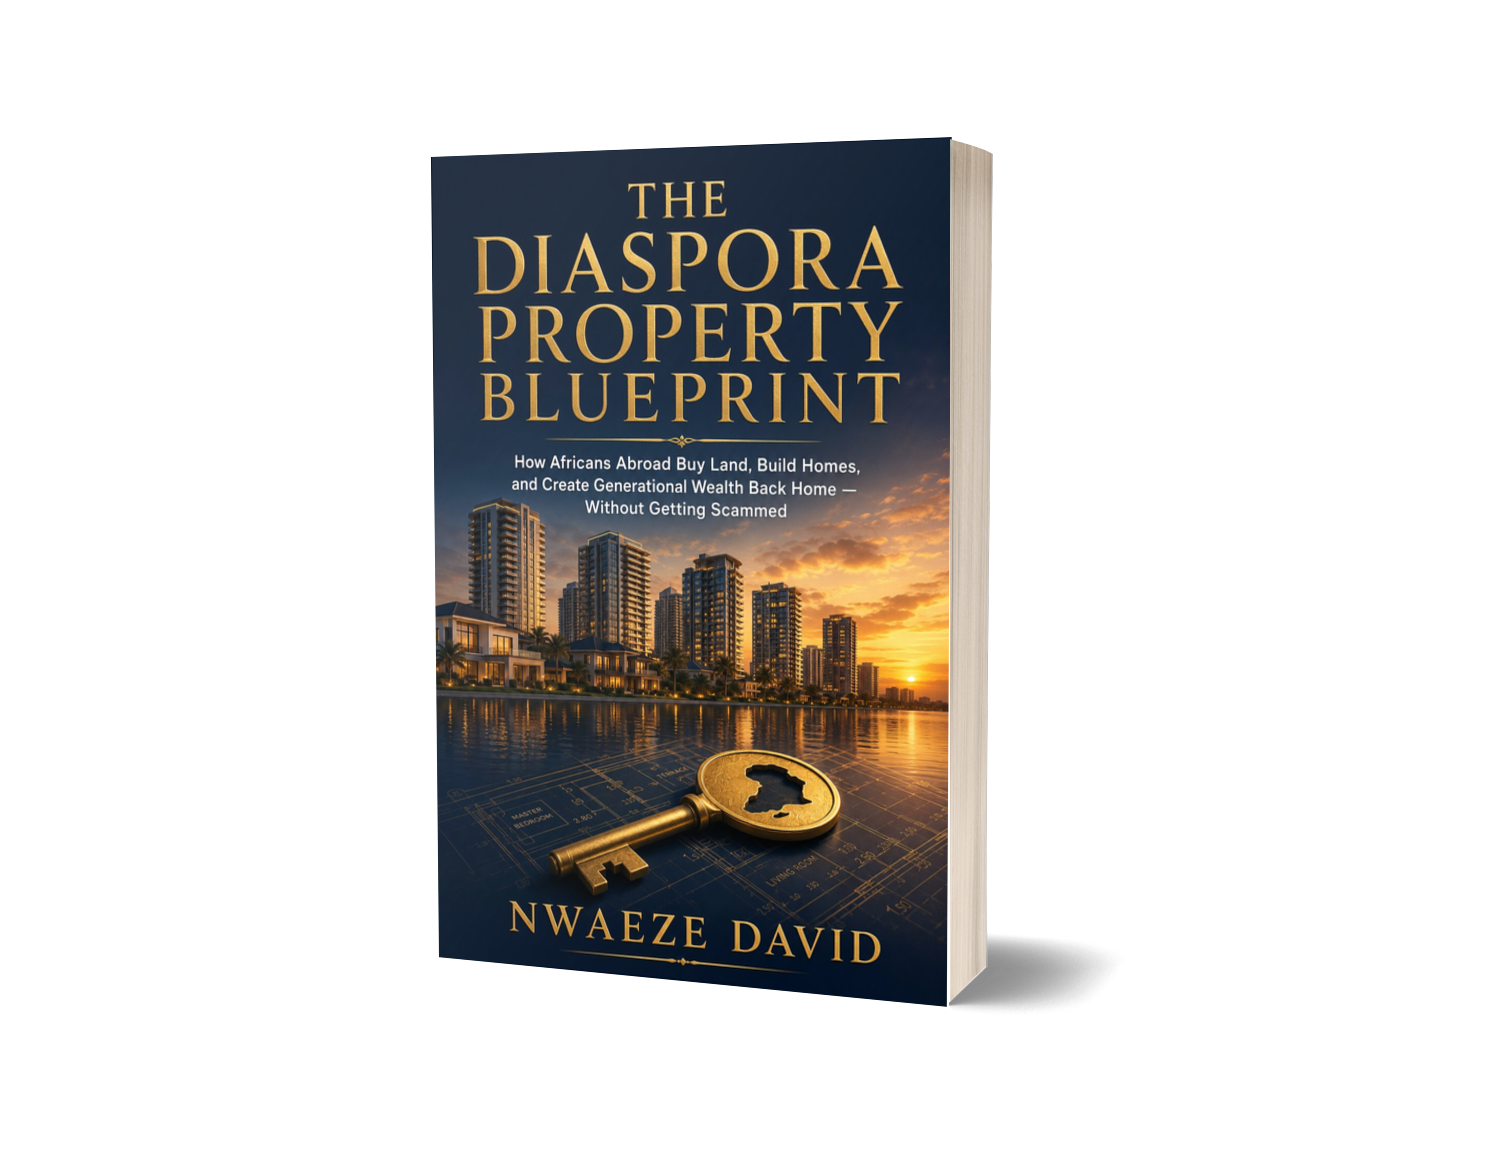
"The Diaspora Property Blueprint is the complete, step-by-step system for buying land and building wealth back home safely, from anywhere in the world."
Get Your Copy →Get more strategies like this in your inbox
Join the newsletter for practical, no-hype lessons on building wealth through property, then step inside the private community where we break down real house hack deals and the numbers behind them.
Keep learning: real estate investing for beginners · how to start investing in real estate with little money · conventional vs FHA loan · how to become a landlord · how to get pre-approved for a home loan.
Education only, not financial or legal advice. Down payment rules, loan limits, mortgage insurance terms, and the self-sufficiency test are set by lenders and government agencies and change over time; figures here are illustrative and marked for verification where noted. Speak to a licensed lender before making an offer on a property.
Written by
Nwaeze David
Nigerian digital entrepreneur, educator and author of three real estate books. He writes practical, honest guides for new investors, working realtors and Africans building back home from abroad.


